

During the COVID-19 pandemic, the German tax authorities introduced various relief measures for businesses, including expanded tax loss utilization rules and a deferral of the commencement of interest accrual on late tax payments. In the context of ongoing tax audits, these measures may provide taxpayers with additional flexibility when negotiating transfer pricing adjustments.
Background: COVID-19 related Measures and their Impact
The utilization of tax losses for corporate income tax purposes is governed by Section 10d of the German Income Tax Act (EStG). A tax loss carryforward is subject to quantitative limitations under the so-called minimum taxation rules, as illustrated in the table below. However, German tax law does not impose any time limitation on the carryforward of tax losses. It should further be noted that different rules apply for corporate income tax (CIT) and trade tax (TT).
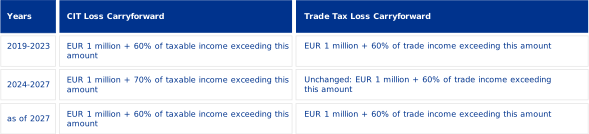
See § 8(1) of the Corporation Tax Act (KStG) in conjunction with § 10d of the Income Tax Act (EStG) and § 10a of the Trade Tax Act (GewStG).
Loss carrybacks are only permitted for corporate income tax (or individual income tax) purposes, but not for trade tax purposes. A loss carryback is generally limited to 1 million euros and is restricted to one year. However, due to the COVID-19 pandemic, the loss carryback has been extended in terms of both duration (two-year loss carryback) and amount (10 million euros). While the two-year loss carryback remains in effect, the original maximum amount of 1 million EUR will apply again starting with the 2024 tax year (the year in which the loss was incurred).
The table below summarizes the rules governing the utilization of tax losses for the 2019 to 2024 tax assessment years.
Loss utilisation (carry-back options)

See Section 233a of the German Fiscal Code in conjunction with various Corona tax relief laws.
In the case of income increases assessed retrospectively, late payment interest is also payable on the tax payments due retrospectively. With effect from 1 January 2019, the German legislature has reduced the interest rate to 0.15 per cent per month (previously 0.5 per cent; see Section 238(1a) of the German Fiscal Code), which represents a long-overdue reduction in the interest rate and is very much to be welcomed. It should be noted, however, that the legislature has provided, as part of the Annual Tax Act 2026, for an increase in the interest rate to 0.3 per cent per month (3.6 per cent per annum) for interest periods commencing on or after 1 January 2027.
With regard to the start of the interest accrual period, the German legislature has also introduced special provisions in connection with the challenges posed by the COVID-19 pandemic, which are outlined below.

See § Section 233a of the German Fiscal Code in conjunction with various Corona tax relief acts.
Practical implications
In transfer pricing cases, it is not uncommon for the outcome of a tax audit to be a set of facts that cannot be fully clarified, coupled with an agreement between the taxpayer and the tax authorities regarding an adjustment to income.
The de facto mutual agreement is an instrument recognised in case law and by the tax authorities, whereby the tax office and the taxpayer can agree on a specific set of facts where clarifying themwould be difficult or involve a disproportionate amount of effort. It is of particular practical importance in the context of tax audits, as it stems from the principles of proportionality and economic rationality (see also “Actual agreement on the facts underlying the tax assessment – application in cross-border cases“; BMF letter of 30 July 2008, amendments of 15 April 2019 and 23 June 2023).
Consequently, if an agreement is reached with the tax authority that the aforementioned solution is feasible, there may also be scope forallocate the loss across the tax years, so that the loss set-off and interest on arrears provisions, as outlined above, can be utilised.
Our KPMG transfer pricing experts are happy to answer any questions you may have.
Ready to talk?

Your contact

Janine Müller
Partnerin, Tax, Head of Global Transfer Pricing Services
KPMG AG Wirtschaftsprüfungsgesellschaft