Things that go bump in the night
October 5, 2026
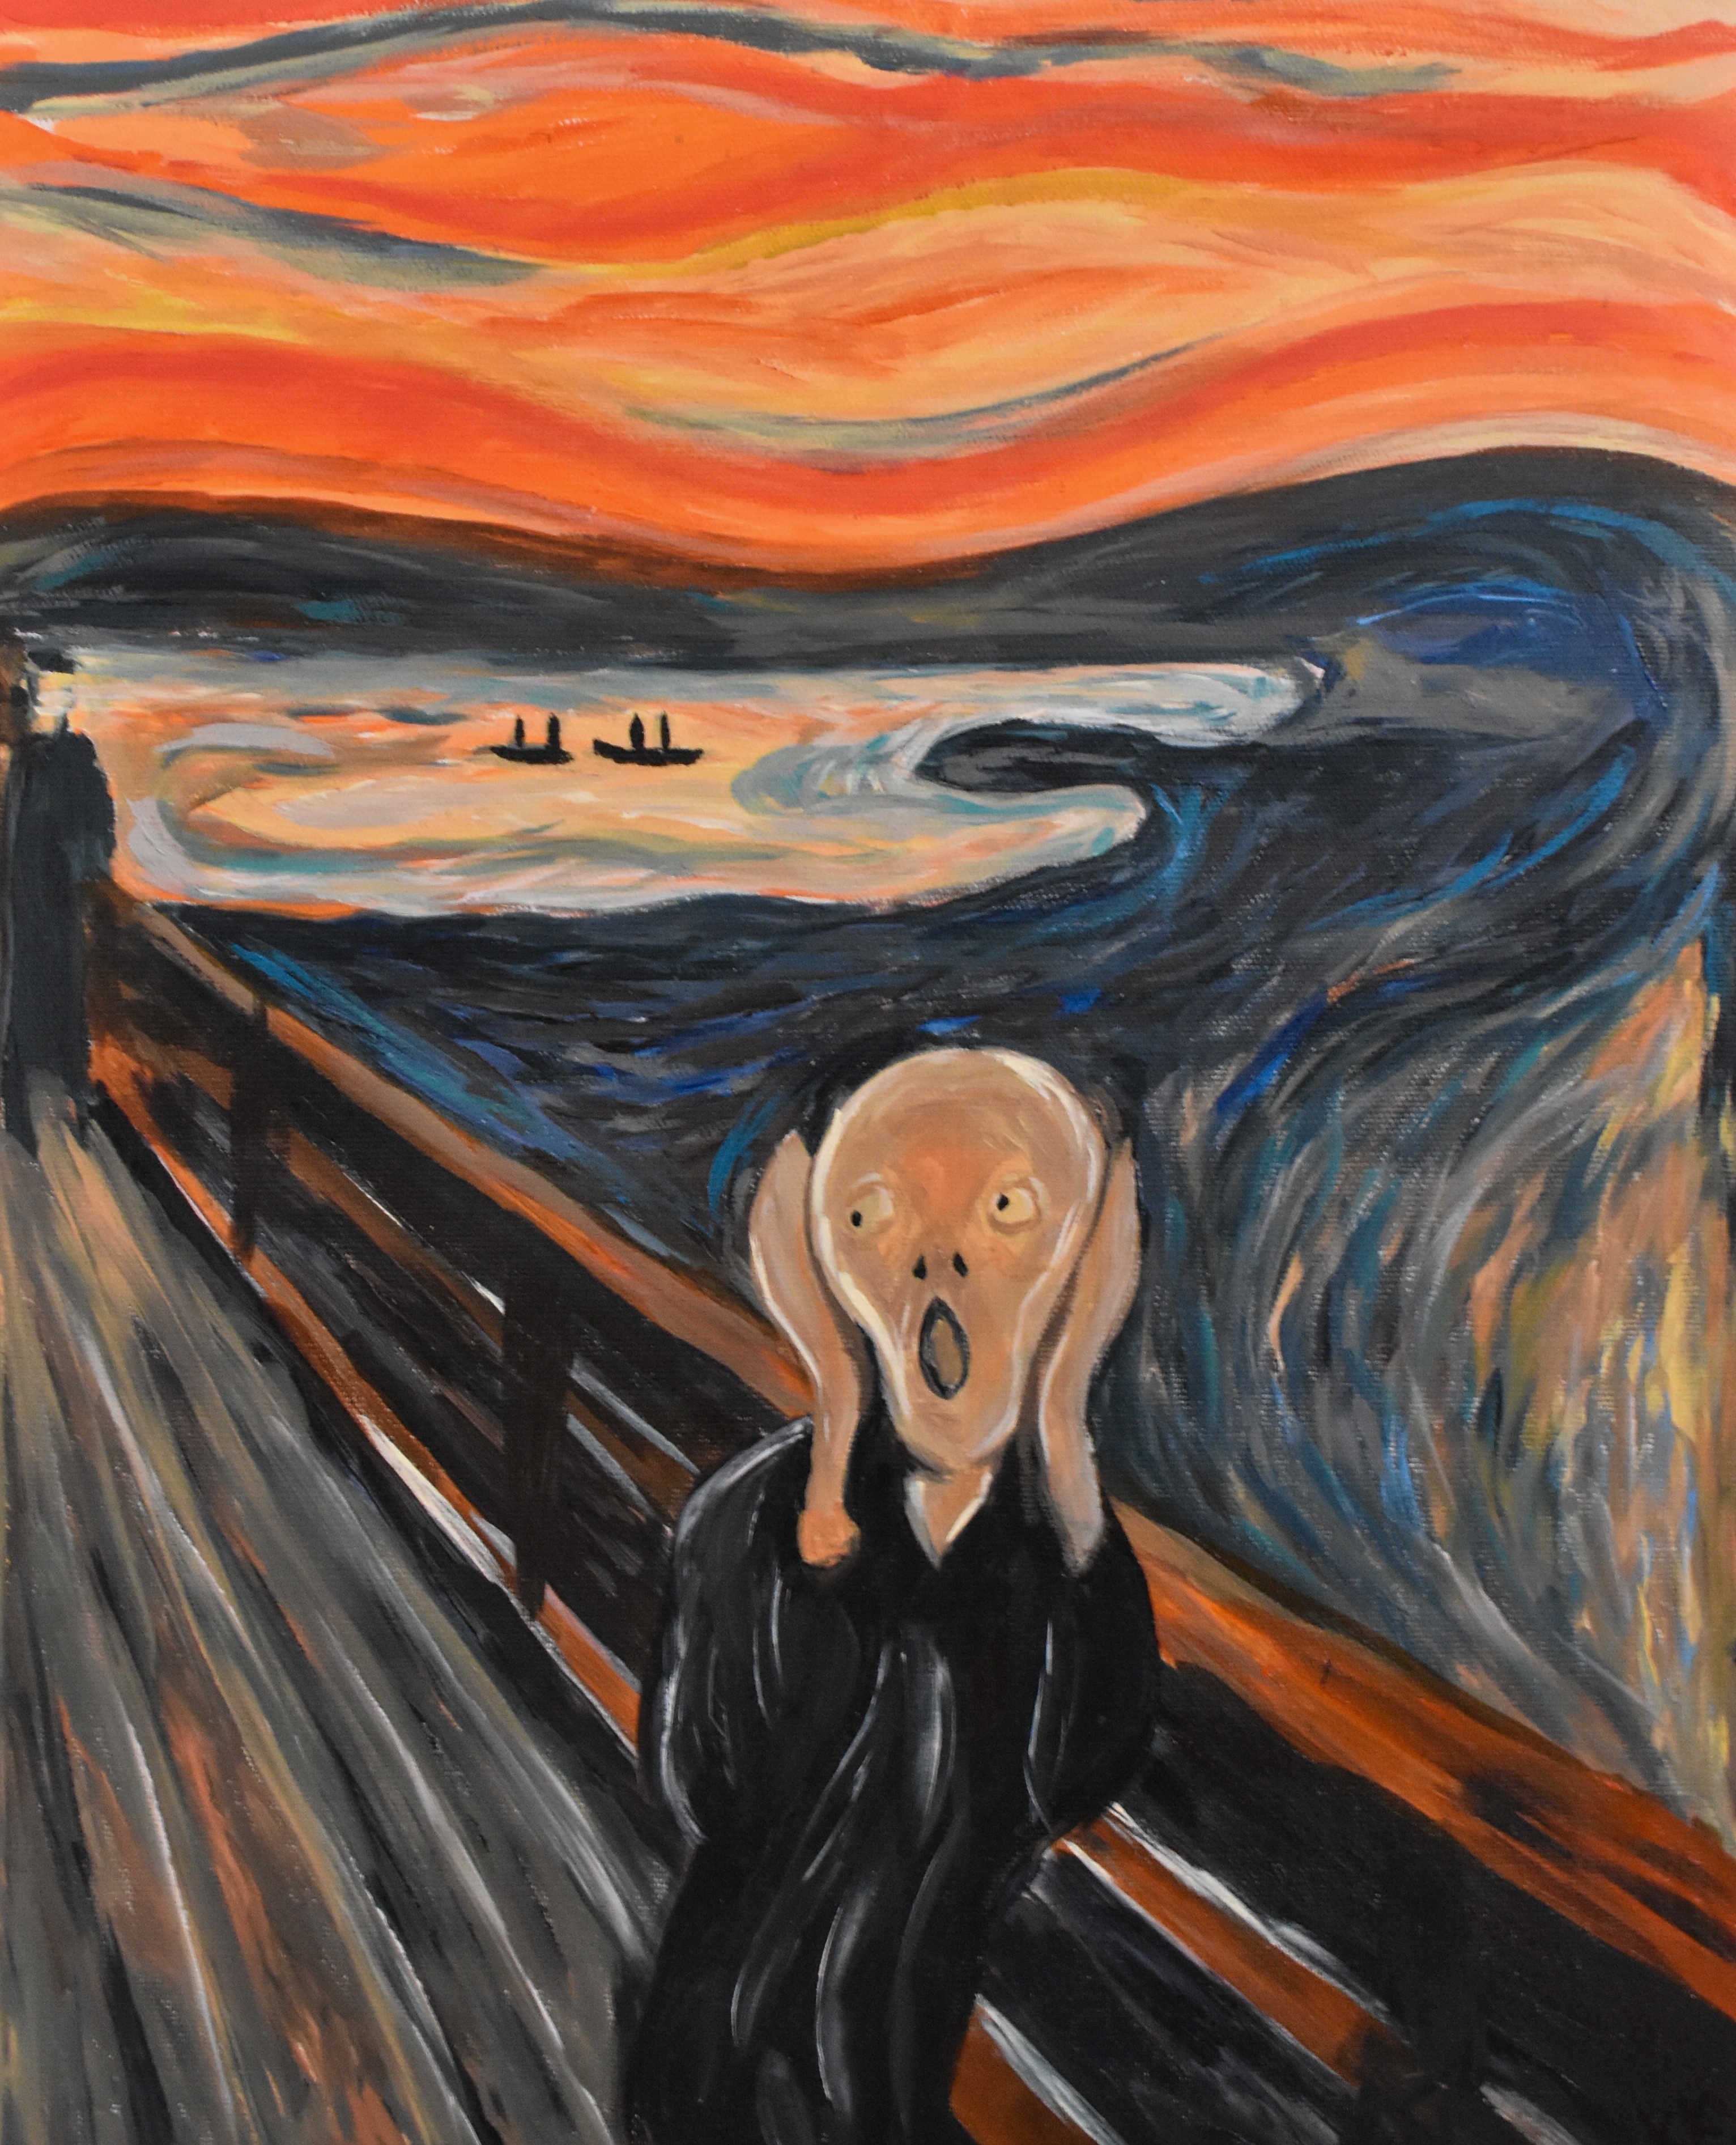
Painter Edvard Munch’s The Scream is a universal symbol of anxiety. It even has an emoji that appears in my text feed all too often. Munch drew inspiration from a sunset walk a year before committing the image to cardboard. Yes, cardboard.
He recalled standing above a narrow inlet as the sky turned blood red: “My friends walked on, and I stood there trembling with anxiety, and I sensed an infinite scream passing through nature.”
That image captures the unease coursing through the economy. Inflation still bites. Unemployment is historically low, yet the labor market feels devoid of opportunity. AI is stoking fears about jobs and control.
Warnings from tech titans about their own products deepen the unease. Little unites the electorate, but backlash to AI cuts across income, age and party lines. The irony is hard to miss: AI and the wealth it generates are propelling the economy while deepening the angst at the kitchen table.
The bond market rout and the Federal Reserve’s about-face on rates are adding to the pain. Consumers experience rate hikes much like inflation: both make everyday purchases more costly. The difference is that higher rates suppress pockets of demand in ways that can lower prices, albeit unevenly.
This edition of Economic Compass counts down the ten shifts keeping me awake at night and shows how they collide. The Fed is trying to cool inflation without breaking an economy propelled by AI investment and the wealth it creates. Both are less sensitive to rates than housing, autos and the other sectors bearing the brunt of higher borrowing costs. Can the Fed deliver immaculate disinflation: lower inflation with little damage to growth or jobs?
The economy has proven resilient enough for the Fed to prioritize its battle against inflation over concern for the labor market. We expect the Fed to hike twice more by early 2027 and hold rates higher for longer to slowly cool inflation. The wild card is the bond market, which has taken on a life of its own and is spurring concerns of a broader tightening in financial conditions.
Sleepless nights
A top ten list
1. The energy shock that will not stay buried.
Gasoline is the price people see everywhere. Diesel is the price they rarely see but shows up everywhere else.
Diesel powers the trucks that stock grocery shelves and the equipment farmers use at harvest. A diesel shock does not stay at the pump; it courses through freight costs, food, construction and nearly all goods that must travel to reach us.
The psychology of fuel price shocks is more combustible than before the pandemic. Consumers and firms no longer see a jump in fuel prices as an isolated event. Five years of escalating costs have created muscle memory. The reflex is to brace for the next increase before the last one fades.
States are suspending fuel taxes ahead of the midterms. That could temporarily dampen price increases but would face an uphill battle against higher refining costs and create a hole in state coffers.
The larger issue is the damage done to global refining capacity. Repairs and deferred maintenance could buoy diesel prices long after the price of crude oil falls. Nearly half of the 100 oil executives that the Dallas Fed recently surveyed worried that the crisis in diesel fuel will take a full year to unwind.
2. The monster in healthcare benefits.
This bout of inflation is more than an energy story; it is a service sector story. Aging is lifting demand for care, while curbs on immigration are worsening labor shortages in the care economy.
Medicaid cuts leave providers less able to raise wages and fill vacancies, so care is rationed. Eldercare is taking the largest hit: in-home care costs are already rising at a double-digit pace.
Healthcare inflation often outlasts the shocks that ignite it. Medical costs kept rising after the recessions of the 1980s broke the back of broader inflation. Cheaper imports and stronger productivity lowered goods prices in the 1990s, but healthcare costs remained elevated.
San Francisco Fed research explains the hard trade-offs: healthcare prices respond more to insurance industry specific forces than to the business cycle. Those factors insulate them from rate hikes, which means that the Fed must hammer goods prices to offset increases in healthcare costs.
Lowering goods prices was easier when cheap imports were flooding into the country. That is no longer the case. Even imports from China, including data center inputs, are rising in price.
The pressure is slow moving because health costs reset through annual contracts. Insurance premiums are poised to increase 14% for small businesses in 2027, which raises those costs more than 25% in two years.
The fallout extends beyond healthcare. Escalating benefit costs are eating into wage gains, while the ranks of those providing unpaid eldercare are swelling.
3. The Fed hunts a ghost it can’t catch.
The Fed cannot pump oil or lower healthcare costs. It can only hammer demand to meet a supply-constrained world.
The trade-off is brutal. The Fed must lower goods prices to offset increases in prices farther from its reach. That means dealing a harder blow to home values, autos, business investment and employment through higher rates.
Central banks usually warn of the pain associated with rate hikes at the start of a tightening cycle. Fed Chairman Kevin Warsh took a different tack in September. He emphasized the economy’s remarkable resilience as the Fed raised rates in September.
Forecasts released by Warsh’s colleagues at that meeting reveal that most do not expect inflation to return to the Fed’s 2% target until 2029 - a full year later than projected in June. Warsh did not participate in the forecast, but he has leaned heavily on an AI-driven productivity boom to derail inflation.
That is a hope, not a promise. There is a catch. Data center construction has proven less sensitive to rate hikes, while the costs are arriving before the productivity gains that could offset them. The risk is that the Fed has to raise rates more aggressively to derail inflation, dealing a greater blow to employment.
4. Bond vigilantes rise from the crypt.
Something else is stirring. When long-term Treasury yields rise, inflation and expected Fed policy may not be the entire story. Investors demand compensation for fiscal risk, policy uncertainty and the sheer stock of debt they are expected to absorb..
Research repeatedly links larger projected deficits to higher long-term interest rates. The direction is clear: more borrowing lifts yields, raises interest costs and widens future deficits. It is a vicious cycle.
What was once an emerging market concern has spread to developed countries in recent days. The difference between French and German 10-year rates is at its highest level since the European sovereign debt crisis in 2011.
Households eventually meet the bond market through mortgage rates and other long-term borrowing costs. The long end can tighten financial conditions even if the Fed is no longer raising short-term rates.
The Fed can tame the inflation premium, not the flood of debt. Foreign investors still want US assets but are more selective, often favoring equities over Treasuries in search of better returns.
5. AI arms race adds to our debt woes.
AI investment is substantial. So is the productivity potential. The question is increasingly how we are paying for it.
For years, the largest tech companies could finance investment from vast internal cash flows. The scale of the AI buildout is changing that. Debt markets, private credit and increasingly creative structures are becoming part of the financing mix.
Debt changes the risk. Companies spending their own cash can absorb mistakes; borrowers must deliver the expected returns. An arms race raises the stakes because one company’s spending becomes another’s reason to spend more.
History offers a warning without denying the innovation. Railroads, electricity and the internet transformed the economy, but not every investment earned a return. Transformative technology does not guarantee that every participant will win.
Bubbles are common. They also pop. That matters when growth depends heavily on the AI boom and the wealth it creates. The Magnificent 7 tech behemoths accounted for about 34% of S&P 500 market capitalization in September. A correction could hit affluent spending and investment at once.
6. AI backlash on the ballot in November.
Finance is only one vulnerability; the buildout needs public consent. Data centers need enormous amounts of electricity and often water. For local communities, the calculation is intensely practical: Who benefits and pays?
A household facing a higher electricity bill does not view a data center as an abstract investment in America’s future. Communities see land use, water and transmission demands, followed by few permanent jobs once construction ends.
Voters will decide 35 data center referendums across eight states on November 3. Most reached the ballot through citizen petitions, showing how quickly the issue became a grassroots fight.
That is a floor, not a ceiling. Even states without a referendum have erected hurdles to data centers.
Regulation trails the technology, but the backlash is gaining speed. November will test the AI boom’s political license to operate. Restrictions need not stop the buildout to slow it; delays and demands that developers absorb more grid and water costs can squeeze margins and stretch timelines.
There is a potential pressure valve. Data centers that cut power use when the grid is strained are different from those that compete with households at peak demand. Flexible demand can unlock capacity and make data centers partners rather than permanent strains on the grid.
Power constraints are accelerating investment in efficient chips, cooling systems and smaller facilities. That can cut delays and improve efficiency, but soaring demand could overwhelm the savings. The buildout needs enough productivity gains to justify its costs.
7. Productivity: trick or treat?
Productivity is the escape hatch. In theory, it allows wages to rise without stoking inflation. We are not there yet.
The firm-level evidence on generative AI is encouraging. Studies show meaningful productivity gains, especially for novice and lower-skilled workers. AI can help employees learn faster, handle more complex tasks and narrow performance gaps.
The economy-wide evidence is less dramatic. Training, software and organizational change must come before the gains show up in measured output.
AI can transform individual firms well before the gains appear in national productivity statistics; the test is whether those gains become large, durable and broad enough to justify the investment boom.
AI helps companies change prices faster, but not necessarily lower them. Recent research shows pricing models can track competitors and react instantly.
When firms use similar models, they may keep prices higher without explicitly coordinating. AI can make it harder for consumers to do price comparisons and keeps prices elevated. The gain in productivity boosts profits more than paychecks, as we have already seen.
8. The gains that fail to boost paychecks.
This may best explain why resilience has failed to resonate. If productivity gains flow to profits and owners of capital rather than to workers’ wages, discontent deepens.
Several leaks separate productivity from pay. Weak bargaining power shifts gains toward profits. AI may initially favor capital and highly skilled workers. Rising healthcare costs absorb compensation that might otherwise appear in wages.
The last point is easy to miss. An economist can tell a worker that employer-paid health insurance is compensation. The worker can just as easily respond that a larger deductible does not feel like a raise.
The economy can therefore produce more while many households feel they are receiving less. That gap between measured compensation and lived experience helps explain weak confidence. For younger workers, the problem is more basic: AI may narrow access to the first job itself.
9. Missing a first rung.
Some of the most consequential labor market changes are invisible because they involve something that never happens. An entry-level job is never posted. A new graduate is not hired. There is no layoff announcement because there was never an employee to lay off.
Stanford research finds hiring has weakened among younger workers in occupations most exposed to AI. The pattern is descriptive, not proof that AI acted alone; tight monetary policy and hiring freezes explain some of it. For a graduate unable to land a first job, the distinction offers little comfort.
Entry-level jobs provide income, industry knowledge, professional judgment and the relationships workers need to advance. AI may make novices more productive once hired while reducing the number of entry-level workers firms need. Fewer entry-level hires today mean fewer seasoned workers tomorrow.
The weakness extends beyond new graduates. Unemployment remains low partly because labor supply and demand are slowing together. Quits rates have plummeted in sectors most exposed to AI; uncertainty about how work will change has made employers more hesitant to hire.
The labor market looks stable from a distance but frozen up close. Long-term unemployment remains elevated despite muted layoffs.
10. The K-loop and the missing social contract.
Higher income households account for a disproportionate share of consumer spending. They are more likely to own financial assets and benefit from higher yields on savings. Borrowers feel the other side of higher rates.
That produces the K-loop. Affluent households sustain spending. Demand remains stronger. Inflation proves harder to extinguish. Fed policy stays tighter. Higher rates bear down most heavily on rate-sensitive sectors and indebted households.
Meanwhile, the benefits of the AI investment boom do not necessarily accrue to the same households bearing the adjustment costs through higher power bills, insurance costs and borrowing rates.
That is more than a distributional problem. It threatens the political durability of the investment boom. Creative destruction creates conflict. A functioning social contract determines whether that conflict becomes progress or backlash..
Rates higher for longer
We expect the Fed to raise rates two more times by early 2027, which would lift the fed funds target to 4.25% to 4.5% range. That would bring short-term rates back to where we were prior to the rate cuts of late 2025. Rates stay there through 2027. Cuts do not begin until 2028.
We expect the 10-year Treasury yield to peak near 5.5% in early 2027, a level not sustained since 2001. That is more than a milestone for markets. It raises borrowing costs across the economy, from mortgages and business loans to the federal debt, as additional Fed rate hikes work through the economy.
Long-term rates face a separate problem: too much debt for sale. The Treasury is borrowing heavily just as the AI buildout sends tech companies, utilities and data center developers to debt markets. Investors will demand higher yields to absorb it. A 5.5% 10-year would show that the bond market, not just the Fed, is tightening the screws.
That is higher for longer in practice. Two-year yields mostly follow the expected path of Fed policy. Longer-term yields reflect how much government and corporate debt investors must buy.
A 5.5% 10-year keeps conventional mortgage rates well above 7%. That would deepen the housing freeze and make it harder for commercial real estate, smaller firms and heavily indebted borrowers to refinance.
Regional and community banks would feel the squeeze as higher yields erode the value of bonds and other assets they own. Less lending would amplify the slowdown, while higher interest costs add to deficits and future borrowing.
Risks. The best case is a broad productivity boom that lowers business costs, cools inflation, supports the AI buildout and lifts paychecks. Inflation could also fall faster than expected, reducing the need for rate hikes. Neither is happening on a large scale yet.
The worst case is a sharp drop in hiring, a financial crisis or a sudden pullback in AI investment. Any of these could stop Fed hikes and pull down short-term rates. Long-term rates may stay high if heavy Treasury borrowing and deficit worries persist, regardless of what the Fed does.
The outcome depends on which force wins: pressure from heavy borrowing on long-term rates or more Fed rate hikes at the short end. If the Fed keeps hiking and recession fears grow, short-term rates could rise above long-term rates, as they did in 2022.
The economy avoided recession then because employers had a record number of job openings to cut before cutting workers. That cushion is gone. The next cut is more likely to be a worker than an opening.
Bottom Line
The economy keeps growing, but too many people do not feel it at the kitchen table. Energy shocks, rising healthcare costs and the AI buildout are keeping inflation hot. Higher rates are colliding with a mountain of public and private debt. Communities are being asked to absorb the costs of innovation without sharing enough in the gains. That is the source of the anxiety. We are back in Munch’s landscape.
Not all of this is fate. Trade barriers, wars and immigration policies that deepen labor shortages add to inflation. This leaves the Fed with few good choices. Policy helped create some of these risks, policy changes can help reduce them. Policy decides who pays for change and who benefits from it.
Munch’s blood-red sky was a sunset, not the end of the world. Night fell and a new dawn followed. Policy must put people at the center of innovation, not leave them in the shadows for that light to shine on more of the electorate. Productivity gains need to boost paychecks, not just profits. That is a choice, which could rebuild trust and renew the social contract. The scream is the warning. Daybreak is ours to deliver.
Be kind; pay it forward.
AI bump for GDP
Real GDP grew at an upwardly revised 2.2% annualized pace in the second quarter, 0.7% faster than initially reported. The largest single adjustment in GDP was in non-residential investment; data center spending ended the quarter a stunning 34% above the initial estimate.
Incomes and consumer spending were revised higher in the first half of the year. Much of the second quarter strength reflected a rebound from weak first quarter gains. The struggling housing market improved modestly, but the gains were short-lived. Inventories were drawn down less than previously estimated, providing a lift to GDP. Government spending flattened, while the trade deficit widened amid a continued surge in imported data center inputs. Some of that demand has spilled over into domestic manufacturing activity as well.
Preliminary data suggest that real GDP accelerated to a 3.5% pace in the third quarter, the strongest in three years. Consumers continued to spend despite a jump in oil prices. Housing lost ground as mortgage rates surged. Orders indicate that the data center boom remained in full force, while inventories began to rebuild. A continuing resolution will cap gains in federal spending; the administration’s request for a 50% increase in defense outlays is also facing resistance. The bond market rout and rise in interest rates is another cost hurdle. The trade deficit is likely to widen further. Data center construction and efforts to rebuild weapons used in conflicts abroad have buoyed imports.
The fourth quarter outlook remains solid, but growth is likely to cool. Consumer spending should slow rather than collapse, with fuel tax holidays at the state level cushioning some of the rise in gasoline prices. Housing activity is poised to contract in response to even higher mortgage rates. Business investment should remain robust, supported by data center construction while inventories continue to rebuild. Government spending will slow while the trade deficit widens on the data centers’ demand for imported equipment and materials.
Fed resumes rate hikes. We expect the Federal Reserve to raise rates at least two times between now and early 2027, removing the accommodation it provided at the end of last year and then some. The Fed hopes to curb the remaining inflation without inflicting undue pain on the economy.
Economic Forecast — October 2026
Dive into our thinking:
Explore more

Subscribe to insights from KPMG Economics
KPMG Economics distributes a wide selection of insight and analysis to help businesses make informed decisions.
Meet our team